UPI Credit Card
UPI Credit Card Settlement Cycles Explained: What Happens Behind the Scenes?
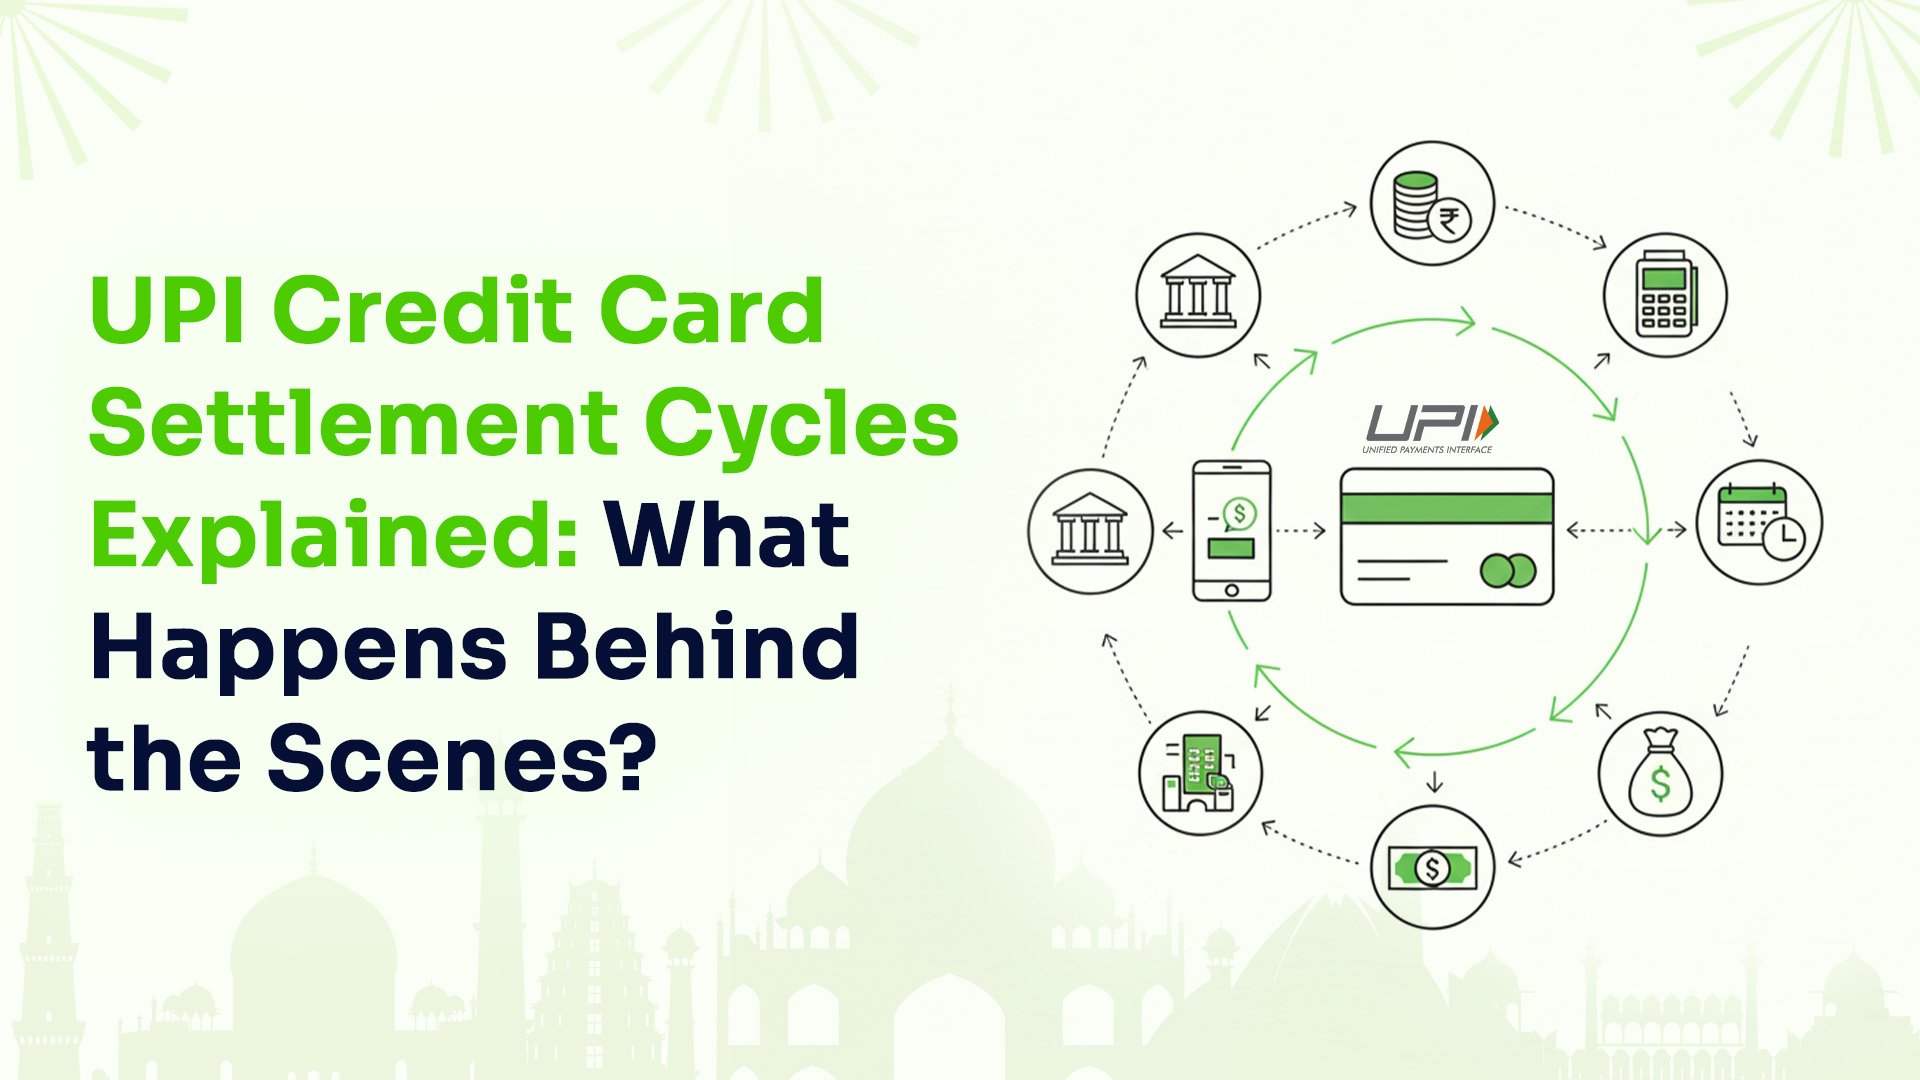
When you scan a QR using a credit card linked to UPI, the transaction feels instant. But multiple systems work together in seconds. Let’s simplify the backend.
Step 1: Payment Initiation
You scan the merchant QR. You choose your RuPay credit card. The UPI app sends a payment request.
Step 2: Network Routing
National Payments Corporation of India routes the transaction.
NPCI connects:
- Issuer bank
- Acquirer bank
- RuPay network
All in milliseconds.
Step 3: Authorisation
The issuing bank checks:
- Available credit limit
- Risk score
- Fraud signals
If approved, the transaction succeeds. If the limit is low or risk is detected, it declines.
Step 4: Merchant Settlement
The merchant’s bank receives funds as per UPI Credit Card settlement cycle. Settlement may occur T+1 or as per bank agreement. The merchant sees payment credited digitally.
Step 5: Customer Billing
The transaction appears in your credit statement.
On statement date:
- Total spend is calculated
- Due date assigned
- Interest-free period activated
If you repay total due before due date, no interest applies.
Why Understanding UPI Credit Card Settlement Cycle Matters
If you transact just after your statement date, you maximise interest-free days. Timing affects cost. Many users ignore this.
Kiwi and Billing Transparency
Kiwi users see:
- Clear billing cycles
- Due dates
- Spending breakdown
This visibility reduces accidental interest charges. In the UPI era, backend systems are complex. But user experience must remain simple. And that simplicity builds trust.
FAQs
1. How long does it take for a UPI credit card payment to settle?
Authorization happens instantly, while merchant settlement typically follows the acquiring bank’s settlement cycle, often T+1.
2. Does UPI credit card offer an interest-free period?
Yes. Like regular credit cards, UPI-linked cards offer an interest-free period if total dues are paid before the due date.
3. Who processes UPI credit card transactions in India?
National Payments Corporation of India manages the UPI network and transaction routing infrastructure.
4. Can a UPI credit card transaction fail after authorization?
It is rare, but network issues or technical failures can cause reversal scenarios.
5. Does billing cycle timing affect interest charges?
Yes. Spending just after your statement date maximises your interest-free period.
Apply
Get a RuPay credit card that works on UPI
Kiwi links an eligible RuPay credit card to UPI, so an everyday QR payment — groceries, fuel, a shop counter — can come from your credit line instead of your bank balance.
- RuPay credit card on UPI
- Pay by scanning any UPI QR
- Cashback on eligible spends
Approval and the card issued depend on your credit score and our partner banks’ criteria. Cashback is subject to the card’s terms.
Related · UPI Credit Card