Credit Card
Best Premium Credit Card in India: Our Picks for 2026
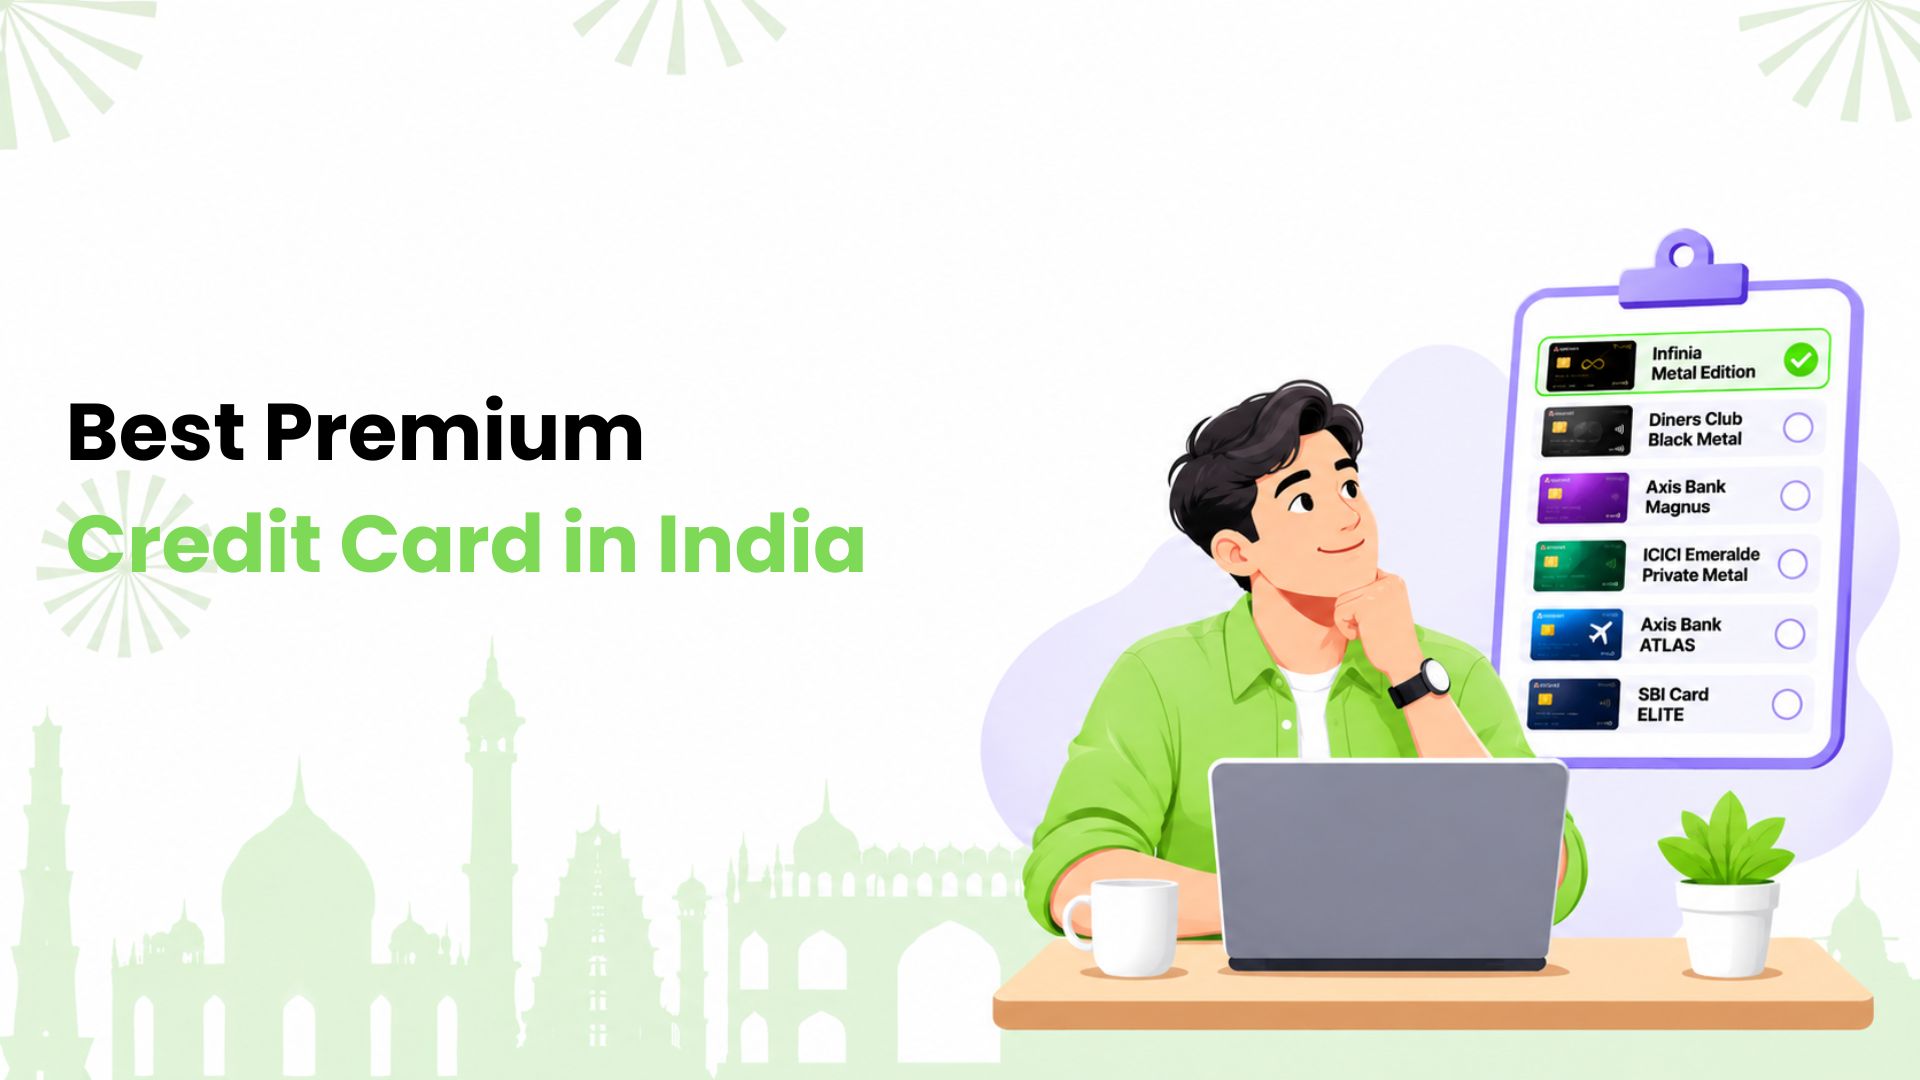
The best premium credit card in India should fit our spending, not change it. For Indian professionals and frequent travellers, we would compare useful rewards, travel benefits and annual costs before applying.
Here are six options we would shortlist for different needs. Our choice depends on the benefits we will use and the value left after fees.
Compare Our Picks by Fees and Spending Style
These are standard published fees before applicable taxes. Personal offers may differ. Renewal waivers depend on qualifying spending and do not automatically remove joining fees. We would confirm current terms before applying.
| Credit card | We would consider it for | Joining / annual fee | Renewal fee waiver |
| HDFC Bank Infinia Metal Edition | Travel redemptions | ₹12,500 / ₹12,500 | ₹10 lakh qualifying annual spend |
| HDFC Bank Diners Club Black Metal Edition | Quarterly spending milestones | ₹10,000 / ₹10,000 | ₹8 lakh qualifying spend in 12 months |
| Axis Bank Magnus | Higher monthly spending | ₹12,500 / ₹12,500 | ₹25 lakh qualifying annual spend |
| ICICI Bank Emeralde Private Metal | Lounge and lifestyle benefits | ₹12,499 / ₹12,499 | Qualifying annual spend over ₹10 lakh |
| Axis Bank ATLAS | Airline and hotel purchases | ₹5,000 / ₹5,000 | No standard annual spend waiver |
| SBI Card ELITE | Dining and groceries | ₹4,999 / ₹4,999 | ₹10 lakh qualifying annual spend |
HDFC Bank Infinia Metal Edition
We would consider invitation-only Infinia for regular flight and hotel bookings. It earns 5 Reward Points per ₹150 of eligible retail spending, including groceries and household shopping. SmartBuy offers accelerated rewards on selected purchases, subject to limits.
Redemption matters: HDFC lists ₹1 per Reward Point for eligible flights and hotels, compared with up to ₹0.30 against the statement balance. Unlimited airport lounge access for primary and add-on members adds value for frequent travellers. We would check booking restrictions and reward limits before estimating savings.
HDFC Bank Diners Club Black Metal Edition
We would shortlist this card for substantial planned purchases across the year. Spending ₹4 lakh in a calendar quarter earns 10,000 bonus Reward Points, subject to eligibility rules. Planned household purchases, dining and travel bookings could contribute.
The card offers unlimited airport lounge access for primary and add-on members, a 2% foreign-currency markup before taxes and accelerated SmartBuy rewards. We would check merchant acceptance and quarterly spending conditions. The Metal Edition’s renewal-waiver threshold is ₹8 lakh in 12 months, distinct from the older card variant.
Axis Bank Magnus
We would assess standard Magnus when large household purchases or travel bookings make higher monthly spending routine. It earns 12 EDGE Reward Points per ₹200 of eligible spending up to ₹1.5 lakh a month; higher earning follows separate limits.
Domestic lounge access requires ₹50,000 of spending in the previous three calendar months, with an initial exception for newly issued cards. We would check exclusions before targeting its fee waiver. Magnus for Burgundy has separate fees, eligibility and benefits.
ICICI Bank Emeralde Private Metal
We would compare this invitation-only card for lounge, dining and leisure benefits. It earns 6 Reward Points per ₹200 of eligible retail spending. Grocery, utility and education spending each have a cap of 1,000 Reward Points per statement cycle; insurance has a separate cap of 5,000 Reward Points.
The card offers unlimited domestic and international airport lounge access for primary and Plus Card members. We would check category caps when estimating rewards on household bills and large payments.
Axis Bank ATLAS
We would consider ATLAS for direct airline and hotel bookings. It earns 2 EDGE Miles per ₹100 of eligible ordinary spending and 5 per ₹100 on qualifying travel purchases. The accelerated rate applies to cumulative eligible travel spending up to ₹2 lakh a month.
We would check who bills our hotel booking, since the merchant and payment route affect eligibility. Spending tiers influence lounge allowances and anniversary benefits. EDGE Miles are a travel reward currency, not cash deposited into our bank account.
SBI Card ELITE
We would shortlist ELITE when groceries, dining and department-store purchases make up much of our budget. It earns 10 Reward Points per ₹100 in these eligible categories and 2 Reward Points per ₹100 on other eligible purchases.
Accelerated-category earning is capped at 10,000 Reward Points monthly, after which the ordinary rate applies under the terms. We would check merchant classifications and redemption value before choosing it for everyday spending.
How We Judge the Value Before Applying
We use our existing budget to estimate:
Net annual value = usable rewards + benefits we would otherwise buy − fees, taxes and extra costs.
For illustration, a card costing ₹10,000 plus 18% GST has an annual cost of ₹11,800. If we receive ₹15,000 in usable rewards and ₹3,000 in benefits we would otherwise buy, the estimated net value is ₹6,200.
We would compare this with a suitable lower-fee card and exclude perks we will not use. We would also check:
- Spending rules: Reward earning, milestones and fee waivers can have different exclusions. Refunds may reverse rewards.
- Redemption: We compare rupee value, expiry dates, transfer limits and booking availability.
- Lounge access: We check terminals, guest charges, spending conditions and the issuer’s current lounge list, including any DreamFolks network updates. Railway lounge access needs a separately stated benefit.
- Overseas costs: We include currency markup, taxes and conversion charges.
- Repayment: We plan to pay the full statement balance by the due date. Interest charges can outweigh rewards.
Before applying, we review income and age criteria and keep our PAN, identity, address and income documents ready. Approval depends on the issuer’s assessment; meeting an income threshold alone is insufficient. Some cards, including Infinia Metal and Emeralde Private Metal, are invitation-only.
Our Premium Card for Travel. Kiwi for the Everyday.
We may already use a premium card for flights, hotel stays and lifestyle benefits. Kiwi can complement it for everyday groceries and dining. With an eligible RuPay credit card, we can pay participating merchants via UPI through Kiwi. Our UPI credit card guide explains the payment flow. Transfers to friends and cash withdrawals are not supported through this facility.
For select eligible users with a card issued through Kiwi from 4 July 2024 onwards, Kiwi Neon Membership costs ₹999 a year plus taxes. It offers 2% cashback on eligible scan-and-pay transactions, subject to exclusions. Monthly cashback is capped at 1% of our credit limit, excluding milestone cashback.
The ₹1.5 lakh eligible annual-spend milestone brings total cashback on eligible spending to 5%, after deducting cashback already earned. With Kiwi Neon Membership, each eligible annual-spend milestone of ₹50,000, ₹1 lakh and ₹1.5 lakh unlocks one airport lounge pass, under programme terms. We would confirm eligibility and the current offer in the app.
Our next rewarding payment need not wait for our next flight. Explore Kiwi, review the terms and conditions, download the app and apply. Approval and the card issued depend on our credit profile and partner-bank requirements. Optional membership fees are separate from card fees.
FAQs
1. Can We Request an Invitation-Only Card?
We can ask our bank or relationship manager to assess eligibility. An enquiry does not guarantee an invitation.
2. Is there One Minimum Salary for Premium Cards?
No. We check the specific card’s requirements. Salaried and self-employed applicants may face different criteria.
3. Does a Fee Waiver Mean a Card is Lifetime Free?
No. We must meet a conditional waiver’s requirements each relevant year. A lifetime-free offer removes the specified card fee under that offer.
4. Can We Take a Guest into a Lounge for Free?
We check guest access separately. Our own complimentary visits do not automatically cover a companion.
5. Do EMI Purchases Earn Rewards?
We check the issuer’s rules. EMI purchases may be excluded from rewards or milestones, and conversions can reverse rewards.
6. Should We Apply for Several Premium Cards Together?
We would compare eligibility first and apply selectively. Formal applications can involve credit-report enquiries.
7. When Should We Review Our Card?
We would review it before renewal or after major benefit changes. Before closing or downgrading, we check rewards, dues and recurring payments.
Disclaimer: This article is for informational purposes only and is not financial advice or a recommendation to apply for any credit card. Fees, eligibility criteria, rewards, benefits and exclusions may change. Please verify the latest terms with the card issuer and Kiwi before applying. Card approval is subject to the issuer’s assessment, and rewards or cashback are governed by applicable programme terms. Use credit responsibly and pay your full statement balance by the due date.
Apply
Get a RuPay credit card that works on UPI
Kiwi links an eligible RuPay credit card to UPI, so an everyday QR payment — groceries, fuel, a shop counter — can come from your credit line instead of your bank balance.
- RuPay credit card on UPI
- Pay by scanning any UPI QR
- Cashback on eligible spends
Approval and the card issued depend on your credit score and our partner banks’ criteria. Cashback is subject to the card’s terms.
Related · Credit Card